The CLARITY Act: What It Is and Why It Matters
Updated September 16, 2026
Stablecoins already have federal rules under the GENIUS Act, but they sit within a much larger digital asset ecosystem. Exchanges, brokers, and other market infrastructure still lack a comprehensive federal market structure framework. The CLARITY Act is designed to address that gap.
On September 15, the CLARITY Act stalled in the Senate after lawmakers failed to secure the 60 votes needed to advance the bill. The Senate rejected the cloture motion 49–50, so it did not move forward with consideration of the legislation.
The result delays the path to a federal digital asset market structure law, but it does not stop regulatory development. The SEC and CFTC can continue shaping digital asset rules through their existing authorities while Congress decides what comes next.
What Is the CLARITY Act?
The CLARITY Act (formally the Digital Asset Market Clarity Act) is a federal bill that would set market structure rules for the broader digital asset market, including cryptocurrencies, token classification, exchanges, and custody.
It would help determine which assets are treated as securities versus commodities, and split oversight between the Securities and Exchange Commission (SEC) and Commodity Futures Trading Commission (CFTC) accordingly. For stablecoins specifically, it would regulate how they interact with the wider crypto ecosystem. However, it would not replace the issuer-specific rules in the GENIUS Act.
What Happens Next for the CLARITY Act?
The CLARITY Act’s path to becoming law in 2026 is now much narrower.
On September 15, the Senate voted 49–50 on cloture for the motion to proceed with H.R. 3633. Because 60 votes were required, the bill did not advance to consideration.
The legislation is still alive, but senators have less time to reach a compromise, bring the bill back to the floor, reconcile any Senate changes with the House version, and send a final bill to the President.
Prediction markets have moved sharply following the delay. On Polymarket, the implied probability of the CLARITY Act being signed into law in 2026 has fallen to around 5%, compared with more than 70% earlier this year.
For now, the broader U.S. digital asset regulatory framework remains unfinished. Congress can still revisit the legislation, while the SEC and CFTC continue developing rules and guidance under their existing authorities.
Here is the timeline so far:
- July 17, 2025: The House votes to pass its version of the bill, with 294 in favor to 134 against
- May 14, 2026: The Senate Banking Committee votes 15-9 to advance its version
- September 15, 2026: The Senate votes 49–50 on a motion to advance the CLARITY Act. The motion falls short of the 60 votes required, so the bill does not proceed to consideration.
- Now: The CLARITY Act remains stalled in the Senate while lawmakers continue debating the shape of a broader U.S. digital asset market structure framework.
Support has been broadly bipartisan, and most lawmakers on both sides already agree that crypto should be regulated. What remains to be negotiated is narrower: how far the bill should go in limiting crypto-related business activities for senior government officials, including the President, to avoid conflicts of interest.
Why Does It Matter?
The CLARITY Act matters because it would extend proven, market-growing rules to the exchanges, brokers, and blockchain networks that make up most of crypto but still lack any federal rulebook.
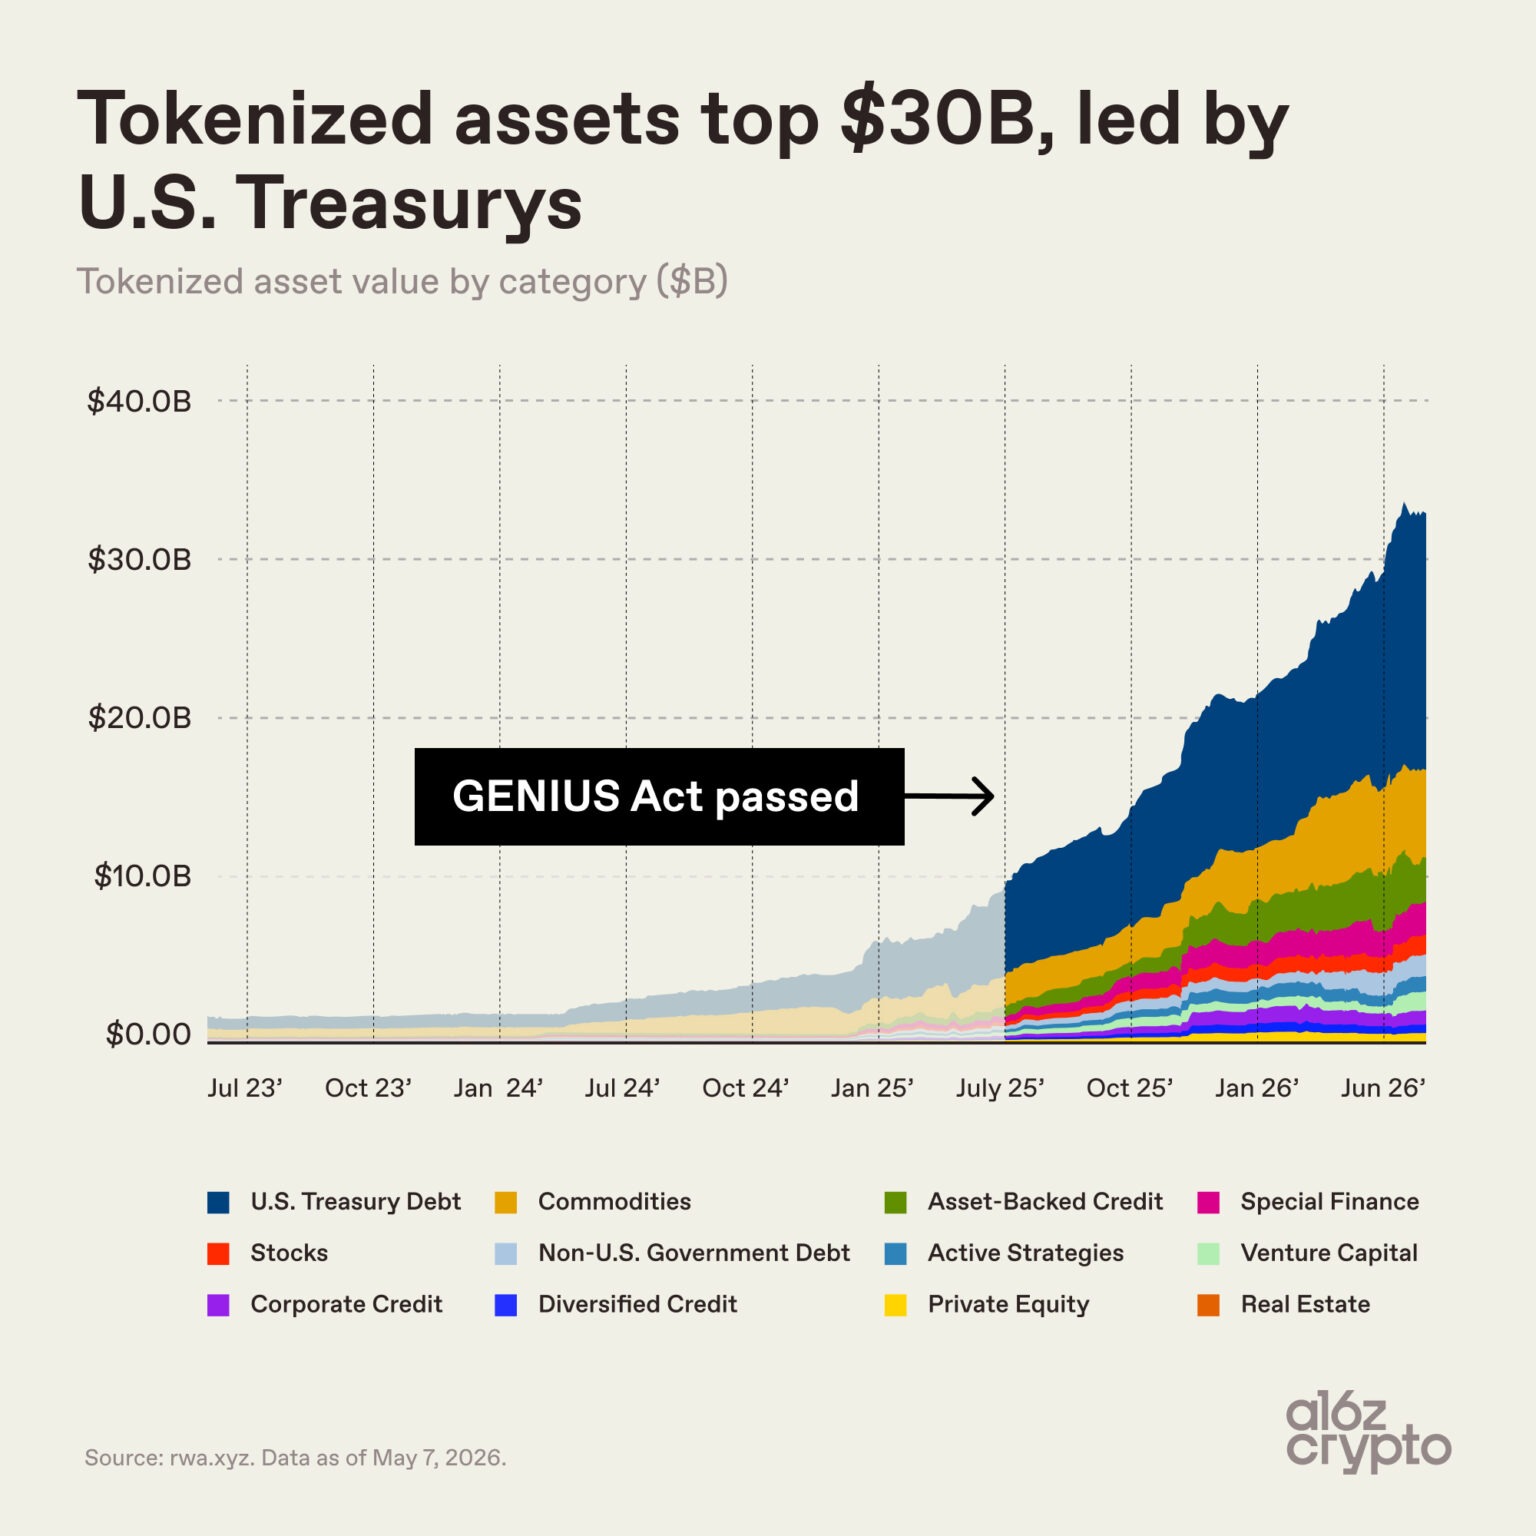
The GENIUS Act created the first federal framework for U.S. payment stablecoins. Since then, the market has grown substantially. Such growth has many drivers, from macro conditions to new institutional demand, but the numbers are notable:
- The stablecoin market has grown past $315 billion, up more than 50% in a year.
- BlackRock, JPMorgan, Citi, Visa, and Mastercard have all deepened their investment in blockchain infrastructure.
- Stablecoins still account for less than 15% of the crypto market by value. The other 85%, (exchanges, brokers, and blockchain networks) remain unregulated at the federal level.
- The EU, UK, UAE, and Singapore already license the crypto exchanges and brokers that the CLARITY Act would address in the U.S. And regulators are not going easy on violators anywhere: crypto firms paid more than $1 billion in AML and sanctions fines globally in 2025 alone.
"With a market as large as the U.S. now bringing in formal oversight — joining the likes of the EU, UK, UAE and Singapore — I expect this will further accelerate the overall global momentum toward regulatory harmonization and, ultimately, institutional adoption of digital assets," says Barbier.
What Would the CLARITY Act Mean for Your Business?
Day-to-day operations are not likely to change right away for businesses that simply accept or send stablecoin payments. The best path is to keep working with a licensed, compliant provider, whether or not the CLARITY Act passes.
Triple-A, for example, is registered with FinCEN in the U.S., has Money Transmitter Licenses in 20+ states, is licensed by the MAS in Singapore, and holds both a Payment Institution and CASP licenses in France, passported across the EU.
The exchanges, brokers, and dealers the CLARITY Act directly regulates are a different story. Over time, they may face new registration, custody, and disclosure requirements that they do not have today. Two further changes could follow:
- Banks and large payment companies that have stayed out of stablecoins because there was no federal rulebook may start offering stablecoin products of their own. For businesses, that means more banks and payment companies to choose from as partners.
- U.S. rules could also start to align more closely with those in the EU, UK, UAE, and Singapore. For a business operating in more than one of those markets, that would mean less work reconciling separate compliance requirements region by region.
Barbier expects large institutions to move in the same way they did after the GENIUS Act passed last year:
Next Steps
The Senate's timeline keeps slipping, and the CLARITY Act may not become law until next year — if it passes this Congress at all.
But the direction it is pointing is not really in question. Exchanges, brokers, and blockchain networks are headed towards more oversight, and U.S. rules are moving closer to the standards already in place in other locations.
Either way, our advice remains the same: work with a stablecoin provider already built for where regulation is heading. Triple-A is a case in point, already with 20+ money transmitter licenses in the U.S., as well as in Singapore and across the EU.
If your existing stablecoin payments are not yet running through a licensed, compliant provider, talk to the Triple-A team.